Market Update
Is 2026 a Good Year to Buy a Home in Hampton Roads?
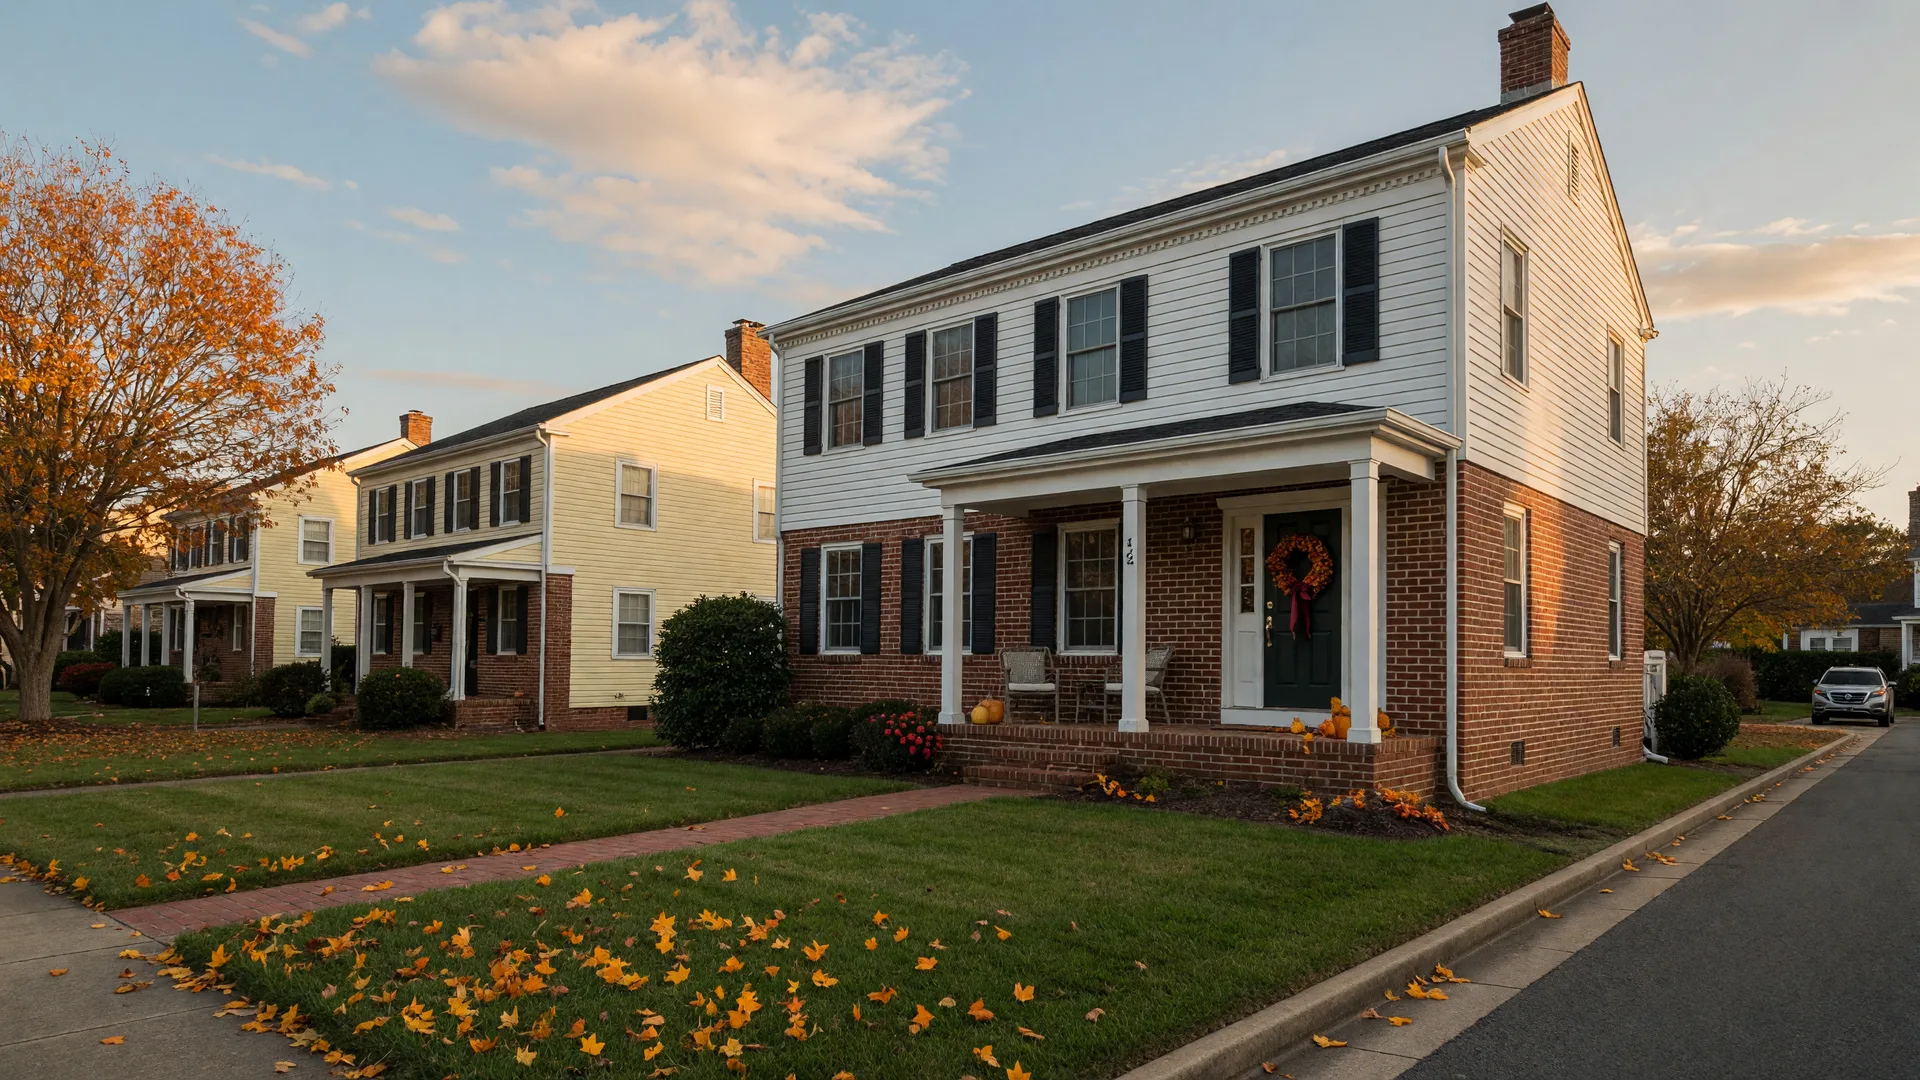
Short answer: 2026 can be a genuinely good year to buy a home in Hampton Roads, but not for the reasons you might expect. Mortgage rates are higher than anyone wanted, yet buyers finally have what they have not had in years: real inventory, time to look, and room to negotiate. As a real estate agent Virginia Beach buyers have trusted for 24+ years, here is how I read the market this fall.
The Hampton Roads market finally has choices
REIN MLS data for August 2026 put the region's median sale price at $388,950, up about 5.1% year over year. Active listings reached 6,120, up 7.2% from a year earlier, the highest inventory Hampton Roads has carried in years. Homes spent a median 27 days on market, and the region held about 2.9 months of supply. That is not a buyer's market, but it is a long way from the multiple-offer sprints of 2021 and 2022. Buyers looking at homes for sale in Hampton Roads can tour without snap decisions, and in many neighborhoods they can negotiate repairs, closing help, or both. My October market update walks through the regional numbers in more detail.
The rate reality is the whole game
The catch is the mortgage rate. The 30-year fixed averaged 7.40% in the week of October 15, 2026, according to Freddie Mac, and Bankrate's index sat at 7.39% on October 21. The forecasts are not friendlier. In October, Fannie Mae revised its outlook up to 7.4% for the fourth quarter and about 7.5% through 2027, and the Mortgage Bankers Association sees 30-year rates staying above 7% through next year. If you have been waiting for 6% mortgages to come back, the honest answer is that the experts no longer expect them any time soon. That matters more than the purchase price, which is why I keep the current numbers updated in my monthly mortgage rate post.
So who should buy in 2026?
The right year to buy is personal, not national. Service members with PCS orders, growing families who need more space now, and buyers who plan to stay put for five years or more all have reasons to move this year that no rate forecast changes. Veterans and active-duty buyers have the strongest card in the deck: a VA loan at zero down, no private mortgage insurance, and no loan limit with full entitlement. At 7.4%, avoiding PMI and a second mortgage saves real money every month. My military and veterans page covers the benefit in detail.
For everyone else, the math comes down to rent versus own. Rents in Virginia Beach hover near $2,200 a month, and a 5% down payment on a $430,000 median home carries a payment not far off that rent once you factor in the tax deduction and building equity. If you can make the payment work on paper, pause, and a slow month, 2026's inventory gives you something rare: leverage.
How to make this year work for you
Get pre-approved before you tour, then shop with an agent who knows which neighborhoods are holding price and which are starting to flex. Ask sellers for concessions, and use them strategically: in a balanced market, you can often negotiate a rate buydown that lowers your payment for the first years without touching the price. The full buying process, start to finish, starts here.
No market is perfect, and 2026 is no exception. But waiting for perfect conditions is how people miss the neighborhood they actually wanted. Let's run your numbers, look at what is on the market, and decide together whether this is your year. I've got you.
Let's Find Out if 2026 Is Your Year
Call or text 757-255-8739, or reach out through the contact page. The first conversation is free and there is no pressure.
Talk to Terry